TL;DR
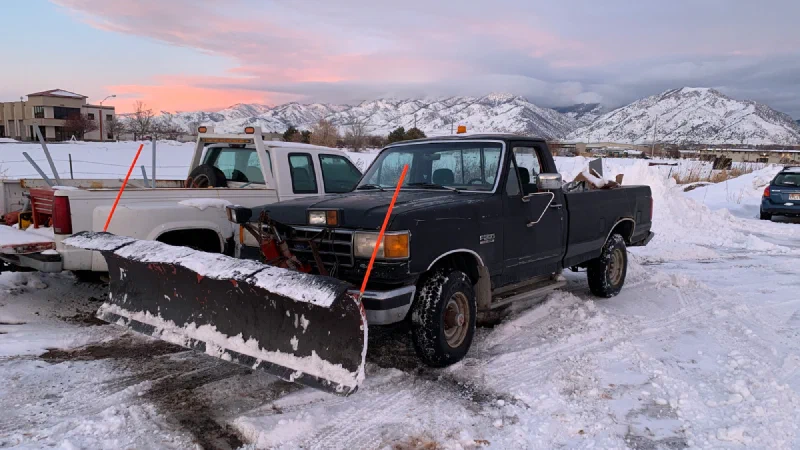
Snow removal insurance is the business insurance a snow-clearing business carries to cover the claims winter work brings: someone slipping on a lot you plowed, a plow blade catching a parked car, or a truck going off the road. Most of it is general liability, with commercial auto for your vehicles and cover for your equipment. Whether you clear a few driveways on the side or plow commercial lots under contract, here’s what clients and insurers will ask for, why snow work is harder to insure than most, and how to get quotes.
Do you need insurance to plow snow?
Usually no law requires a snow removal business to carry insurance, but in practice you’ll often need it before you can get work:
- Property managers, condo corporations and commercial clients commonly ask for proof of liability insurance, and to be named on your policy as an additional insured, before you start.
- Some cities license snow plow contractors. Ottawa’s licensing by-law, for example, requires proof of at least $2 million in motor vehicle liability and $2 million in general liability insurance for a snow plow licence (Schedule 4, sections 5 and 6), and the City publishes the wording a certificate must include. Check with your own municipality.
- Any vehicle on the road needs auto insurance, and plowing for pay is business use (see the FAQs below).
Even a one-person driveway business carries real risk. As a sole proprietor, a claim against your business is a claim against you, and a single slip-and-fall can cost more than many seasons of work.
What snow removal insurance covers
Snow removal insurance isn’t one policy. It’s a set of coverages, and which ones you need depends on what you own and what your contracts ask for.
| Coverage | What it covers | Who usually needs it |
|---|---|---|
| General liability | Injuries to other people and damage to their property, such as a slip on a lot you cleared or a damaged curb, plus your legal defence. Completed operations cover protects you after you’ve left the site | Every snow removal business |
| Commercial auto | Your plow trucks and other road vehicles, and the damage they cause | Anyone plowing with a road vehicle. Ask your auto insurer; it’s a separate policy |
| Hired and non-owned auto | Claims involving vehicles you rent or that workers drive for you | Businesses with staff or rented trucks |
| Tools and equipment | Snow blowers, plow blades, salt spreaders and skid steers, on site, in transit or in storage | Anyone with equipment worth insuring |
| Commercial property | A shop, yard or salt storage you own or rent, and what’s inside it | Businesses with a base of operations |
| Business interruption | Lost income while you can’t work after an insured loss, such as a fire at your yard | Businesses that depend on one site or a few key machines |
| Professional liability | Claims that you didn’t do what the contract promised, such as missing a salting visit | Contractors with written service-level contracts |
Equipment breakdown cover, for sudden mechanical or electrical failure, is also available from some insurers. Our contractor insurance guide covers the same coverages for other trades.
Why snow removal is hard to insure
Snow removal can be harder to insure than many small businesses, and the premiums can be higher than new operators expect. Insurers commonly point to:
- Slip-and-fall claims. Ice can form again hours after you’ve plowed and salted, and injuries from falls can be serious and expensive.
- Claims that arrive late. A claim can come months after the snow has melted, when it’s hard to prove what you did on the day.
- Contracts that shift the risk to you. Many snow contracts include clauses that make the contractor responsible for claims, even ones the property owner might otherwise have faced.
- Few insurers writing it. Some insurers limit how much snow work they take on, which leaves fewer options at renewal.
You can’t change the weather, but good records, clear contracts and a clean claims history are what insurers look for.
What insurers ask to see
Insurers that write snow removal businesses commonly ask for more detail than for other trades. Have this ready:
- How long you’ve been in business, and your claims history
- What you do: residential or commercial, plowing, salting, sidewalks or roofs, and whether you also do landscaping
- A list of your sites and clients, and the type of property (parking lots, retail, condos, driveways)
- Copies of your contracts, especially the insurance and indemnity clauses
- How you keep records: logbooks, a scheduling app or GPS
- Your vehicles, equipment and drivers, and whether you use subcontractors
A new operator with no history can still get insured, but expect more questions and fewer options.
Keep records of every visit
Records are your best defence against a slip-and-fall claim, because they show what you did, when, and in what conditions. For every visit, log:
- The date and the times you arrived and left
- The weather and ground conditions, such as freezing rain or a crust of ice
- What you cleared and where you salted or sanded
- Photos, or GPS data from your truck or app
- Who did the work, and any problem you saw or reported to the client
Keep the records for as long as a claim could come in, which can be years. Some cities require them anyway: Ottawa’s by-law has licensed contractors record the site, the client and the date and time of every visit (section 17).
Ontario’s 60-day notice rule for snow and ice
In Ontario, someone injured by snow or ice on private property usually has to give written notice within 60 days. Under section 6.1 of the Occupiers’ Liability Act, added in 2020, a claim for personal injury caused by snow or ice generally can’t go ahead unless written notice, with the date, time and location, is served within 60 days on the occupier or on the snow removal contractor they hired.
What it means for you as a contractor:
- If you receive a notice, send it to your client straight away, and to your insurer. The law expects each to pass a notice on to the other.
- Your records matter more. A notice can arrive weeks after the visit, so you’ll need to show what you did that day.
- There are exceptions. The rule doesn’t apply where the person died, and a judge can allow a late notice if there’s a reasonable excuse and it doesn’t prejudice the defence.
Other provinces don’t have the same rule, so check yours. See also business insurance in Ontario.
What to check in a snow removal contract
Most disputes in snow removal come down to the contract. Before you sign, check:
- The scope: which areas you clear, and which you don’t (sidewalks, stairs, roofs, loading docks)
- The trigger: the snowfall depth that starts a visit, and how fast you must respond
- Salting and sanding: whether it’s included, when, and who supplies the salt
- Hold harmless or indemnity clauses: what claims you’re agreeing to take on, and whether your insurance covers them
- Insurance requirements: the limits, whether the client wants to be an additional insured, and how long cover must last
- Records and reporting: what you must log and share, and when
If a clause asks you to take on more risk than your policy covers, talk to your insurer before you sign. A lawyer can review the contract too. When the client asks for proof, see what a certificate of insurance is.
Workers’ compensation for snow removal
If you have workers, you’ll generally need to register with your province’s workers’ compensation board, such as the WSIB in Ontario. As the owner, you’re usually not covered yourself: in Ontario, sole proprietors outside construction are covered only if they apply for optional insurance. How your work is classified affects the rules, so ask your board. Workers' compensation is a provincial program, separate from your business insurance.
What affects the cost of snow removal insurance
What you pay depends on the size of your operation and the risk in your contracts. Insurers commonly look at:
- Residential or commercial work, and the type of properties
- How many sites you clear, and whether you salt
- Your vehicles, equipment and drivers
- Your claims history and years in business
- The limits and deductibles you choose, and what your contracts require
- Your records and contracts
For how insurers work out a premium, and what pushes it up or down, see how much business insurance costs. The only reliable number is a quote for your own business.
Get quotes before the snow arrives
Insurers can take time to quote snow work, and clients often ask for proof before the first snowfall, so start early in the fall. Tell us about your business and we’ll refer you to licensed brokers who can quote.