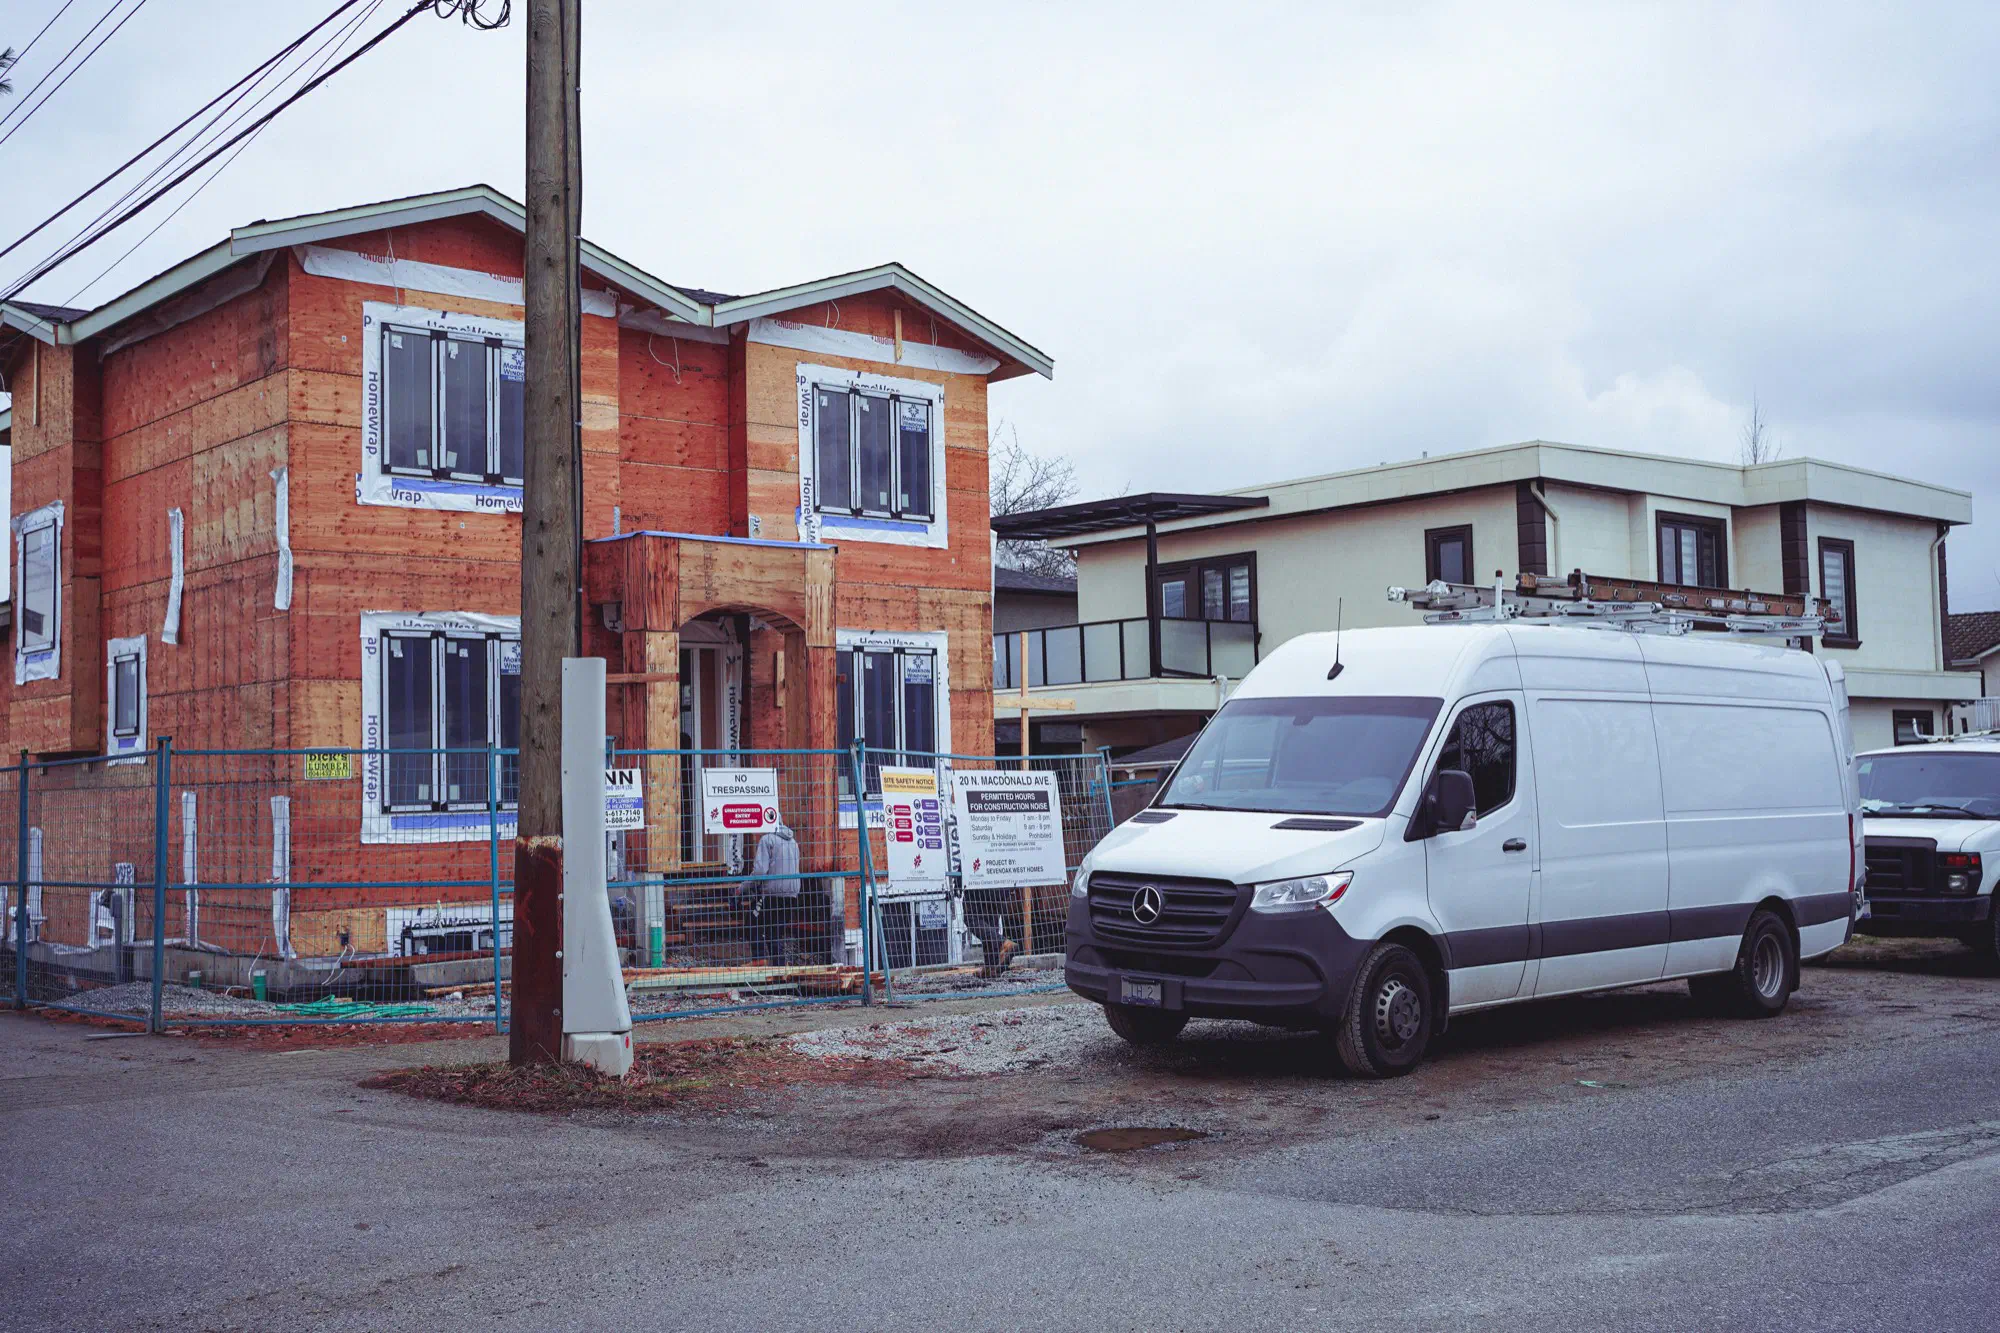
Commercial General Liability Insurance in Canada
Also called general liability or CGL insurance. If your business is blamed for injuring someone or damaging their property, commercial general liability insurance is the policy that responds.
What is commercial general liability insurance?
Commercial general liability insurance, often shortened to CGL and also called general liability insurance, pays when someone outside your business claims that it caused them bodily injury or damaged their property. It typically covers your legal costs to defend the claim, and any damages a court orders you to pay, up to your policy limit.
The person making the claim is a third party: a customer, a client, a supplier or another business. Your own employees and subcontractors aren’t third parties, so claims from them fall outside this policy.
Who needs commercial general liability insurance?
Most businesses that deal with the public or work on someone else’s property do. A good test: if a customer, client or visitor could be hurt, or their property damaged, because of what you do or where you do it, this coverage is relevant to you.
What does a real claim look like?
These examples are illustrative, not real cases. In each one, defending the claim costs money whether or not it succeeds, which is what the policy is built to pay for.
What limits and deductibles mean
Two numbers on a policy decide how much protection you actually have, and a third decides what you pay first.
- Per-occurrence limit: the most the policy pays for a single claim or incident.
- Aggregate limit: the most it pays for all claims over the policy period, usually a year.
- Deductible: the amount you pay yourself on each claim before the insurer pays.
A higher limit means more protection and usually a higher premium. A higher deductible usually lowers the premium but means you pay more out of pocket when a claim happens. If a claim could be larger than your limit, an umbrella policy adds cover on top of it. Many client contracts and leases set a minimum limit, so check yours before you choose one.
General liability vs professional liability
They cover different risks, and many businesses need both.
| General liability | Professional liability | |
|---|---|---|
| Covers | Bodily injury or property damage you cause to others | Claims that your advice, design or service cost a client money |
| Example | A customer slips in your office and is injured | A consultant’s plan fails and the client sues to recover the spend |
| Commonly needed by | Most businesses that deal with the public or work on others’ property | Consultants, designers, IT and licensed professionals |
For the other half of the picture, see professional liability insurance.
How much does general liability insurance cost?
There isn’t one price. What you pay depends on how much risk your business carries and the cover you choose. The only reliable number is a quote for your own business, and Clearly Rate doesn’t set prices. The insurer does.
What affects the price
- Your industry and the work you do
- Annual revenue
- The number of employees you have
- How long you’ve been in business
- The building or premises you work from, if any
- Your claims history
- The limit and deductible you choose
How to keep your premium down
Describe your work accurately, since gaps between what you do and what you told the insurer can cause problems at claim time. Choose a limit that matches your contracts rather than the biggest one available. Ask what a higher deductible would save, and whether you’re comfortable paying that amount yourself. Ask whether combining coverages into one policy is available.
Is general liability insurance required?
No general law requires it, but you’re often required to have it in practice.
| Situation | What’s usually required |
|---|---|
| You lease commercial space | The landlord typically requires liability cover, often with a minimum limit |
| You sign contracts with clients | Many contracts set a minimum limit and ask for proof of cover before work starts |
| You work on someone else’s property | Property owners and general contractors commonly ask for proof of insurance before you start |
| You sell at markets, events or venues | Organizers and venues commonly ask for proof of cover |
When a landlord or client asks for proof
You’ll usually be asked for a certificate of insurance: a short document from your insurer that confirms you have a policy, the type of cover, the limits and the dates it’s in force. Some contracts also ask you to name the landlord or client as an additional insured, which extends the policy’s protection to them for claims connected to your work. Ask your insurer how to request both, and check that the wording matches what your contract requires.
What general liability doesn’t cover, and what does
Commercial general liability responds to claims from third parties. It isn’t a catch-all. Here’s where common risks go instead:
| Risk | What usually covers it |
|---|---|
| Injuries to your own employees | Your provincial workers’ compensation board, such as WSIB in Ontario, not a private liability policy |
| Damage to your own building, equipment or stock | Commercial property insurance |
| Claims that your advice or service cost a client money | Professional liability insurance |
| A data breach or cyberattack | Cyber insurance |
| Accidents involving your vehicles | A separate auto policy |
| Intentional or criminal acts | Generally not covered by any liability policy |
| Promises in a contract that go beyond your normal legal duty | Usually excluded, so ask your insurer |
Exclusions vary by insurer, so read the list before you buy.
Business insurance FAQs
What is commercial general liability insurance in Canada?
How much does $2 million in liability insurance cost?
What's the difference between public liability and commercial general liability?
Does general liability cover my employees if they're injured?
Do I need it if I work from home or as a sole proprietor?
Does it cover damage to my own equipment or premises?
Ready to compare?
Tell us about your business and we'll refer you to licensed insurers.