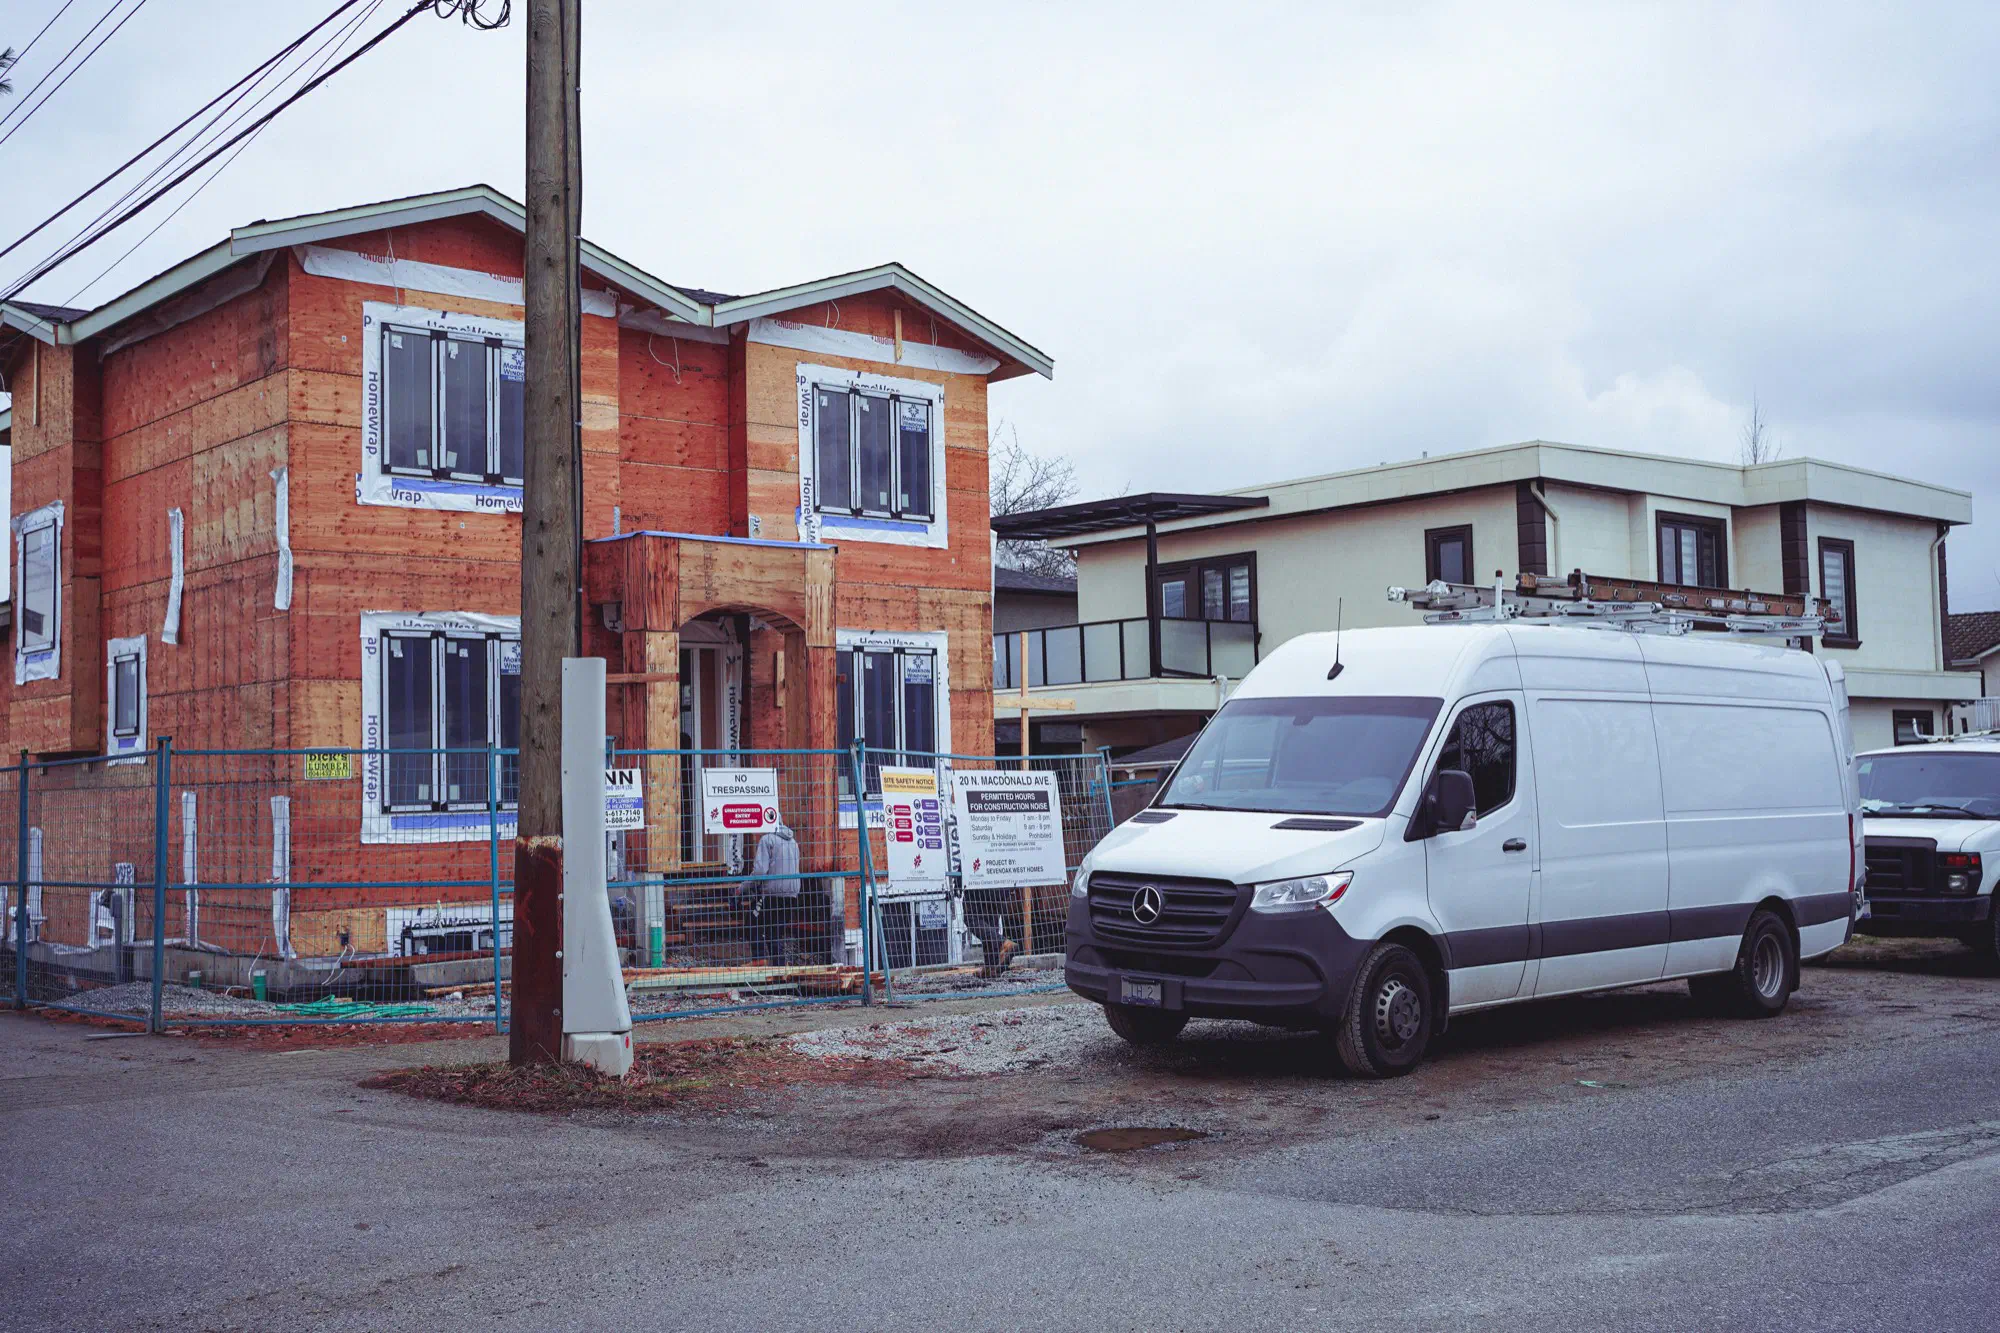
Contractor Insurance in Canada
Contractor insurance protects trades and construction businesses from the cost of things going wrong on the job: a client’s property is damaged, someone is hurt on site, your tools are stolen or finished work fails months later.
What is contractor insurance?
Contractor insurance isn’t one policy. It’s a package for trades and construction businesses, usually built around commercial general liability insurance and cover for your tools and equipment, with other coverages added to fit your trade and the work you take on. It’s sometimes called construction insurance.
What’s in it depends on what you do. A painter working in occupied homes, an electrician on commercial sites and a general contractor running renovations all face different claims, and insurers price each trade separately.
Which coverage does a contracting business need?
Your trade, the jobs you take on and your contracts decide it. Most contractors start with general liability and tools cover, then add what their work calls for. Contractor liability insurance is the part clients ask about first.
- Protects against
- Injury to others and damage to their property caused by your work
- Commonly needed by
- Almost every contractor who works on someone else's property
- Protects against
- Your shop, yard, office, stock and stored tools
- Commonly needed by
- Contractors with a shop, a yard or a storage unit
- Protects against
- A building and its materials while it's being built or renovated
- Commonly needed by
- General contractors and owners on a build or major renovation
- Protects against
- Theft of or damage to your tools and equipment, wherever they are
- Commonly needed by
- Every trade that relies on its own tools
- Protects against
- Claims that your design, plans or advice cost a client money
- Commonly needed by
- Design-build firms and contractors who draw plans or specify work
- Protects against
- Lost income while a covered loss, such as a fire, shuts you down
- Commonly needed by
- Contractors who rely on a shop, yard or workshop to operate
Pollution liability is also worth asking about if your trade handles fuel, chemicals, mould or asbestos, since general liability commonly excludes pollution.
Who needs contractor insurance?
A good test: do you work on other people’s property, with tools and materials, for clients who could hold you responsible if something goes wrong? Then contractor insurance is commonly expected, whether you’re a company or working on your own.
What does a real contractor claim look like?
These examples are illustrative, not real claims. Whether a policy pays depends on its wording, the limits and the deductible.
The third example is the one contractors most often misread: insurance commonly pays for the damage your work causes, not for fixing the work itself.
Common claims by trade
Every trade has its own pattern of claims, which is one reason insurers classify and price each one separately. These are common examples, not a full list.
| Trade | A common claim | Cover that usually responds |
|---|---|---|
| General contractors and renovators | Damage to the client’s property, or to a neighbouring unit during the work | General liability |
| Electricians | A fire traced back to wiring after the job | General liability, including completed operations |
| Plumbers | Water damage from a leak or a burst connection | General liability, including completed operations |
| Roofers | Rain getting in during a tear-off, or materials falling on a car below | General liability |
| Painters | Overspray on vehicles or neighbouring property | General liability |
| Landscaping and excavation | Striking a buried gas, water or cable line while digging | General liability |
| Any trade | Tools stolen from a job site or a vehicle | Tools and equipment cover |
What clients and general contractors will ask for before you start
Often the moment a contractor first needs insurance is when a client, property manager or general contractor asks for proof before the job starts. Expect some or all of these:
Keep the wording your contract uses, and check that the certificate matches it. A certificate that names the wrong party or the wrong limit can hold up the start of a job.
Hiring subcontractors, or working as one
Who insures what depends on where you sit in the job. As a rule of thumb, everyone on a project carries their own liability insurance and insures their own tools.
| You are | What you usually carry | What to ask others for |
|---|---|---|
| The general contractor | General liability, tools and equipment, and builders risk if the contract says so | A certificate of insurance from every subcontractor before they start |
| A subcontractor | Your own general liability and tools cover | The contract’s insurance requirements, so your certificate matches them |
| An independent contractor working alone | Your own general liability and tools cover, as a sole proprietor or company | Nothing usually, but expect clients to ask you for proof |
A general contractor may be held responsible for damage caused by a subcontractor who has no insurance of their own, which is why collecting certificates matters. Subcontractor insurance isn’t a separate product: it’s the same contractor package, bought by the sub.
Contractor insurance vs builders risk vs the client’s home insurance
People search for “construction insurance” to mean two different things: cover for the contractor’s business, or cover for the building being worked on. They’re separate policies.
| Policy | What it insures | Who usually buys it |
|---|---|---|
| Contractor insurance | Your business: claims against you, your tools, your completed work | You, the contractor |
| Builders risk (course of construction) insurance | The building and materials while it’s being built or renovated | The owner, or the contractor if the contract says so |
| The client’s home or building insurance | The client’s own property and their own liability | The client |
The client’s policy isn’t there to cover your mistakes. If your work causes the damage, their insurer may pay the client and then try to recover the cost from you, which is when your liability insurance matters.
How much does contractor insurance cost?
The price depends on what you do and how much of it you do. Insurers commonly look at:
- Your trade and the work itself, including work at heights, below ground, with heat or flame, or near utilities
- Residential or commercial work, and the size of your typical job
- Revenue and payroll, and whether you have employees or hire subcontractors
- The limits you need, which your contracts often set
- The value of your tools and equipment
- Years in business and your claims history
- The deductible you choose
To keep the cost down, describe your work accurately (a mismatch can cause trouble at claim time), keep tools locked up and recorded, practise good site safety, pick a deductible you could actually pay, and compare quotes from more than one insurer. Websites quote all sorts of figures, but none of them can tell you what your business would pay. A quote for your own business is the only reliable number.
Is contractor insurance required?
No single law requires every contractor to carry liability insurance, but in practice it’s often a condition of getting the work.
| Who may ask | What they usually want |
|---|---|
| Clients and homeowners | Proof of liability insurance before you start |
| General contractors | A certificate of insurance, a minimum limit and sometimes additional insured status |
| Property managers and condo corporations | Proof of cover before you work in the building |
| Public and commercial projects | Insurance requirements set out in the tender or contract |
Some licensing bodies and municipalities may also ask for proof of insurance for certain trades or permits, so check the rules for your trade and province.
What contractor insurance doesn’t cover
A contractor package covers a lot, but not everything. Here’s where common gaps go:
| Not covered | What usually covers it |
|---|---|
| Repairing or redoing your own faulty work | Generally excluded; the damage it causes may be covered |
| Injuries to your own workers | Your provincial workers’ compensation board, such as WSIB in Ontario |
| Your vehicles | A separate commercial auto policy |
| The building under construction | Builders risk insurance |
| Errors in your design, plans or advice | Professional liability insurance |
| Pollution, such as a fuel spill or mould | Pollution liability, if it’s added |
| Penalties in your contract for finishing late | Generally not insurable |
Get ready: what an insurer will ask
Having these answers ready makes quotes faster and more accurate:
- Your trade or trades, and roughly what share of your work is in each
- Whether you work on homes, commercial buildings or both
- Your annual revenue and payroll
- How many employees you have, and whether you hire subcontractors
- The size of your largest typical job
- The value of your tools and equipment
- Any certificate, limit or additional insured requirements in your contracts
- Your claims history
Contractor insurance FAQs
Does a homeowner's insurance cover a contractor working in their home?
Do subcontractors need their own insurance?
Do I need contractor insurance as a sole proprietor?
Is WSIB the same as liability insurance?
What is a certificate of insurance?
Does contractor insurance cover my work after the job is finished?
How much liability coverage should a contractor carry?
Ready to compare?
Tell us about your business and we'll refer you to licensed insurers.