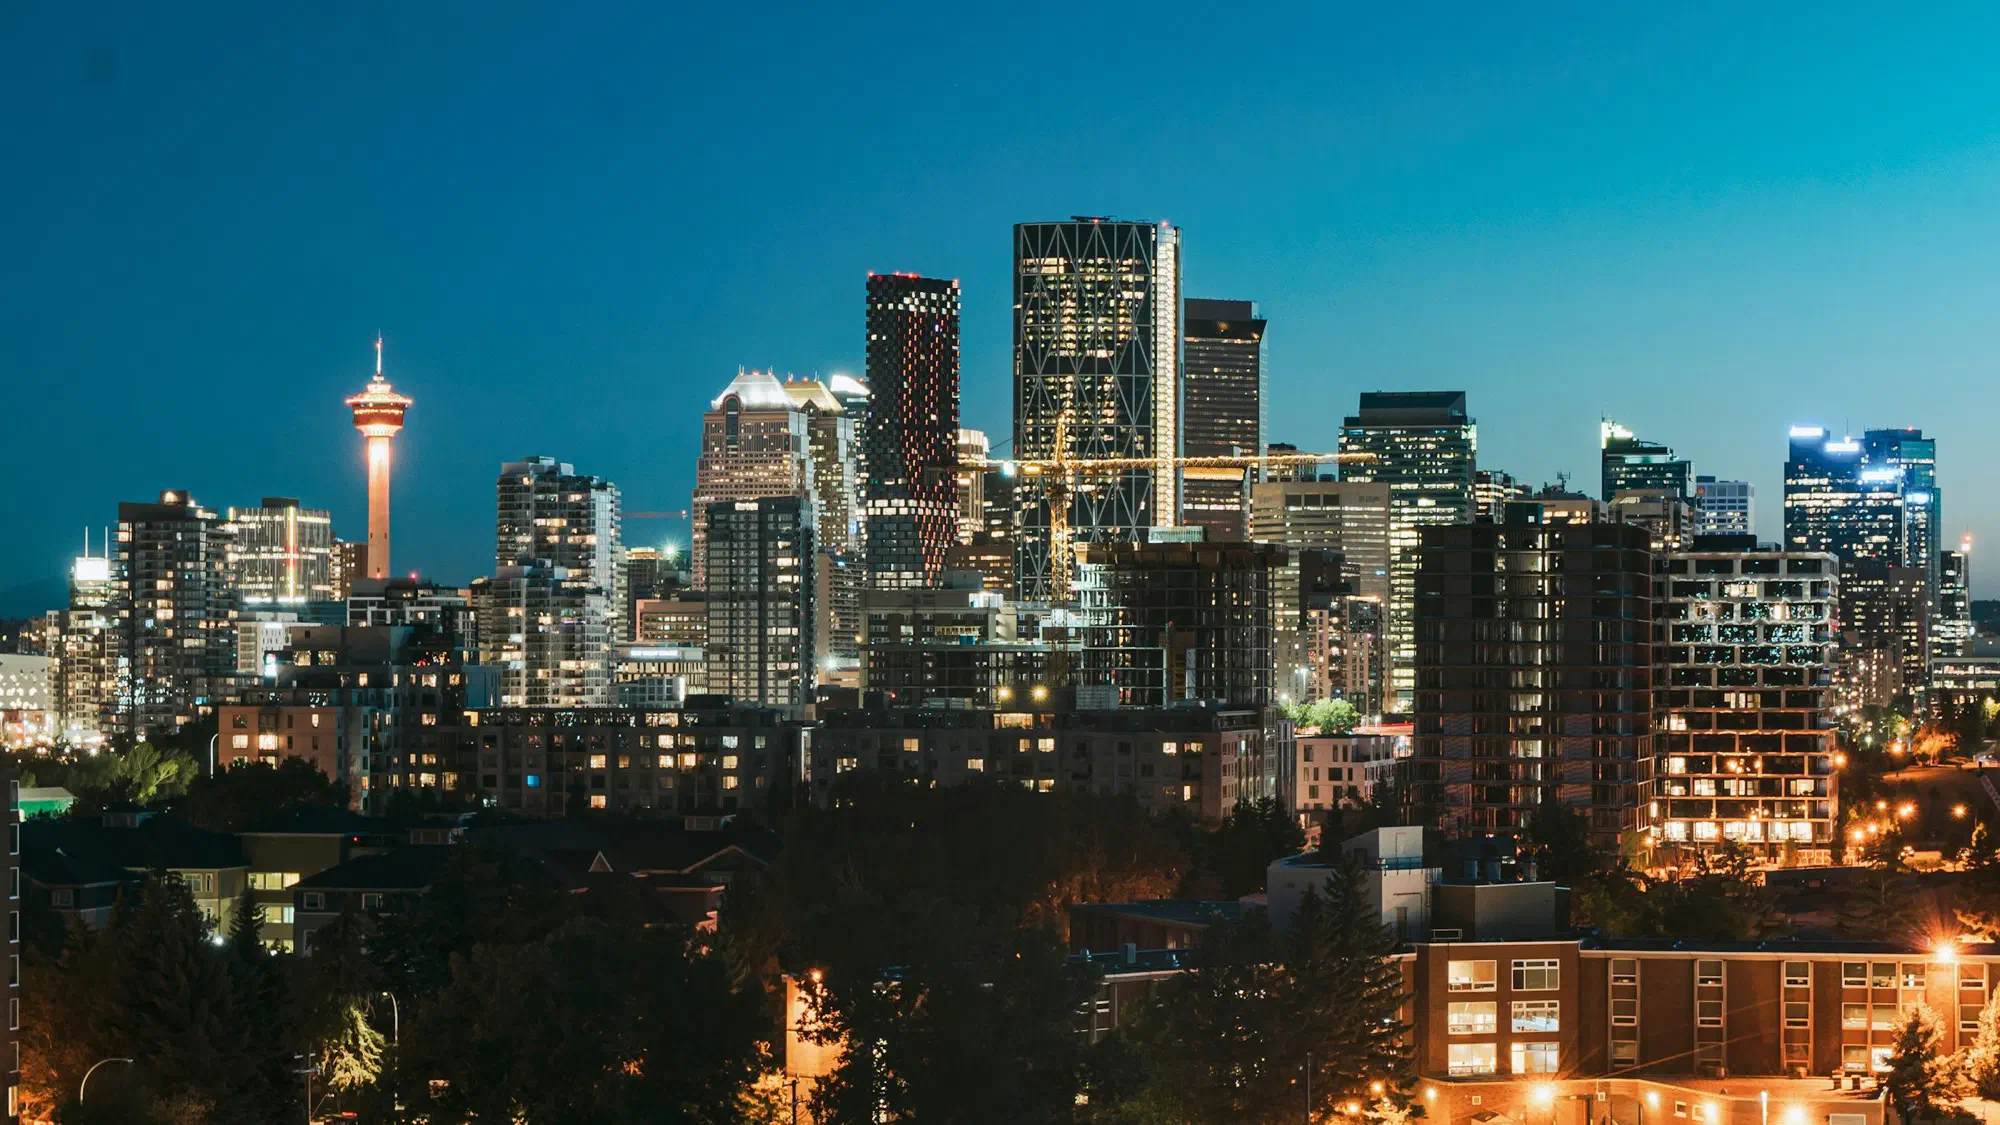
Business Insurance in Alberta
Business insurance in Alberta isn’t required by one law, but WCB-Alberta, professional regulators, landlords and clients can all require parts of it. Here’s what applies to small businesses and sole proprietors across the province, and the Alberta risks, from hail to wildfire, to check a policy for.
Is business insurance mandatory in Alberta?
No Alberta law requires every business to carry business insurance. Some requirements do apply, though: employers in compulsory industries have to register with WCB-Alberta, every vehicle needs auto insurance, some regulated professions require professional liability insurance, and commercial leases and client contracts commonly require liability insurance. In practice, that’s where most Alberta businesses first need cover.
| Who may require it | What they may ask for | Why |
|---|---|---|
| WCB-Alberta | An account and premiums for your workers | Required for employers in compulsory industries, within 15 days of hiring a first worker. Employers in exempt industries can choose to buy it. It’s a provincial program, not a private policy |
| The law, for vehicles | Auto insurance | Required for every vehicle on Alberta roads, including business vehicles, and sold by private insurers. It’s a separate policy, and not something Clearly Rate refers |
| Your professional regulator | Professional liability insurance | Some regulators require it of their members. For example, CPA Alberta requires it of every registered firm. Check with your own regulator |
| Your landlord | Liability insurance, and often insurance on your contents and improvements | Commercial leases commonly require it, and often ask you to name the landlord as an additional insured |
| Clients and general contractors | A certificate of insurance and a minimum liability limit | Many contracts set both before work starts. See what a certificate of insurance is |
| Your municipality | Proof of insurance for some business licences | Some licences may ask for it, depending on the business and the city |
This differs from B.C. in two ways. WCB-Alberta coverage depends on your industry, where WorkSafeBC covers employers in almost every industry, and Alberta’s auto insurance is sold by private insurers rather than a public one. This is general information, not legal advice.
Searching for liability insurance in Alberta can turn up personal and auto liability too. This page is about business liability: general liability for injury or damage your business causes, and professional liability for claims about your work. A home or tenant policy’s personal liability usually excludes business activity.
What business insurance do Alberta businesses usually need?
Your work, your premises and your contracts decide it. Most Alberta businesses start with general liability, then add the coverages their risks call for. General liability insurance in Alberta is the cover landlords and clients ask for most, and small business insurance in Alberta is usually a package of several of the coverages below. Commercial insurance is the umbrella term for all of them.
- Protects against
- Injury or property damage you cause to others
- Commonly needed by
- Most businesses that deal with the public or work on others' property
- Protects against
- Claims that your advice or service cost a client money
- Commonly needed by
- Consultants, designers, IT and regulated professionals
- Protects against
- Damage to or loss of your equipment, stock and premises
- Commonly needed by
- Businesses with equipment, stock or a location
- Protects against
- Lost income when a covered event forces you to close
- Commonly needed by
- Businesses that depend on a location or equipment
- Protects against
- Costs after a data breach or cyberattack
- Commonly needed by
- Businesses that hold customer data or take payments online
- Protects against
- Claims about how a company or nonprofit was managed
- Commonly needed by
- Incorporated businesses and nonprofits with a board
Building or renovating? Builders risk insurance, often called course of construction insurance in Alberta, covers the building and materials while the work is under way. For other coverage you may hear about, such as umbrella, equipment breakdown and crime, see other business insurance coverage.
Business insurance by type of Alberta business
What an Alberta business needs depends a lot on what it does. These are common starting points, not rules.
- Protects against
- Damage to clients' property, injury on site and stolen tools
- Commonly needed by
- General contractors, renovators and every trade
- Protects against
- Claims that your advice or work cost a client money
- Commonly needed by
- Consultants, designers and other professionals
- Protects against
- Claims that an error in your work cost a client money
- Commonly needed by
- CPA firms, bookkeepers and tax preparers
- Protects against
- Customer injuries, fire, theft and lost income
- Commonly needed by
- Retail stores, restaurants, cafés and other storefronts
- Protects against
- Business equipment, stock and clients visiting your home
- Commonly needed by
- Freelancers, online sellers and anyone working from home
- Protects against
- Claims against directors and officers about decisions they made
- Commonly needed by
- Incorporated businesses, nonprofits and charities with a board
What does a real claim look like for an Alberta business?
These examples are illustrative, not real claims. Whether a policy pays depends on its wording, the limits and the deductible.
Alberta risks to check your policy for
Hail is the risk Alberta is known for. The August 2024 Calgary hailstorm was the second-costliest insured event in Canada’s history, behind the 2016 Fort McMurray wildfire, according to the Insurance Bureau of Canada. Before you buy, ask how a policy handles each of these:
| Risk | Where it shows up | What to ask |
|---|---|---|
| Hail | Calgary and the rest of southern and central Alberta, mostly in summer | Is there a separate deductible for wind and hail? How are older roofs, skylights and outdoor signs covered? |
| Overland flood | River valleys, as the 2013 floods in Calgary and southern Alberta showed | Is overland flood covered, optional or excluded? |
| Sewer backup | Basements, especially after heavy summer storms | Is sewer backup an add-on, and what’s its limit? |
| Wildfire | The north, the foothills and the mountain parks, as Fort McMurray in 2016 and Jasper in 2024 showed | Does business interruption include civil authority cover if an evacuation order closes you? |
| Winter | Province-wide: frozen pipes, heavy snow on flat roofs, and ice at your entrance | Is water damage from a burst pipe covered, and what do you have to do to keep the heat on? Who clears snow and ice, and is that in writing? |
Insurers price each address on its own, so hail exposure, the age of your roof, flood zones and local claims history can change what the same cover costs from one part of the province to another. The commercial property and business interruption pages explain those coverages in more detail.
WCB-Alberta: what small businesses should know
WCB-Alberta is Alberta’s workers’ compensation board. It covers your workers if they’re hurt on the job, and it’s a provincial program, not something you buy from a private insurer. Business insurance, such as general liability, usually excludes injuries to your own workers. Five points from WCB-Alberta’s own pages matter most to small businesses:
This matters most for contractors and anyone who hires trades or cleaners. WCB premiums are set by WCB-Alberta, by industry, and are separate from what you pay for business insurance.
Professional liability in Alberta
Professional liability insurance in Alberta is often set by a regulator. Some professions have their own program or minimum, and searches for it mostly turn up regulators’ own pages. A few examples:
- Lawyers in private practice are covered through the Alberta Lawyers Indemnity Association, the Law Society of Alberta’s insurance program.
- CPA firms registered with CPA Alberta have to carry professional liability, with minimum limits set by the size of the firm. See accountant insurance for how those rules work.
- Health and other regulated professions each have a college that sets its own rules, and many require members to carry professional liability.
If you belong to a regulated profession, check your college or regulator first: it may require a minimum limit, or point you to a program run for the profession. If you don’t, clients may still ask for proof of cover before they hire you. See professional liability insurance for what it covers.
Alberta laws behind common business claims
Two Alberta statutes sit behind many of the claims small businesses face. This is general information, not legal advice. A lawyer can tell you how they apply to you.
Who regulates insurance in Alberta?
The Alberta Insurance Council licenses insurance agents, brokers and independent adjusters, and you can check that someone is licensed on its website before you buy. Insurance companies are regulated by Alberta’s Superintendent of Insurance, part of Treasury Board and Finance.
If you have a complaint about an insurer, the usual route is:
Clearly Rate isn’t an insurer or a broker. We refer you to licensed brokers, as our licensing page explains.
How much does business insurance cost in Alberta?
The price depends on your business, and insurers commonly look at:
- Your type of business and the work you do
- Revenue and payroll, and how many people you employ
- Where in Alberta you are, including the property’s exposure to hail, flood and wildfire
- The age and type of your roof, and any past hail damage
- The value of your building, equipment and stock
- The limits your lease and contracts require
- The deductible you choose, including any separate wind and hail deductible
- Years in business and your claims history
Some costs sit outside a business insurance quote: WCB premiums are set by WCB-Alberta, and vehicles are insured on their own policies. Alberta has no provincial sales tax, so nothing is added to your business insurance premium at the till; insurers pay Alberta’s insurance premiums tax themselves.
To keep the cost down, describe your work accurately and look after the premises: keep the roof in good repair, ask about a backwater valve if your basement is at risk, and keep the heat on through cold snaps. Choose a deductible you could actually pay, and review your cover each year. Websites quote all sorts of figures, but none of them can tell you what your business would pay. A quote for your own business is the only reliable number. Our guide to how much business insurance costs explains how insurers work it out.
Business insurance across Alberta
Clearly Rate refers businesses anywhere in Alberta, from Calgary and Edmonton to Red Deer, Lethbridge, Medicine Hat, Grande Prairie, Fort McMurray and rural Alberta. The coverages are the same everywhere in the province, but the risks aren’t. Business insurance in Calgary has to reckon with summer hail, business insurance in Edmonton with long winters and river valleys, and a business in the north with wildfire season, and insurers rate each address on its own. Operating in other provinces too? See business insurance in Ontario and business insurance in B.C..
Get ready: what an insurer will ask
Having these answers ready makes quotes faster and more accurate:
- What your business does, and roughly what share of your work is in each activity
- Your annual revenue and payroll
- How many employees you have, and your WCB account number if you have one
- Your address, and whether you own or rent the premises
- The age of your roof, and any hail damage history
- The value of your building, equipment and stock
- Any limits or certificates your lease or contracts require
- Your claims history
When quotes come back, compare at least two or three on the same coverages, limits and deductibles before you compare prices. See how to compare business insurance quotes.
Alberta business insurance FAQs
Is business insurance mandatory in Alberta?
Do I need WCB coverage if I'm self-employed in Alberta?
Does WCB cover me as the owner of a corporation?
Does business insurance cover hail damage in Alberta?
Is "liability insurance" in Alberta the same as personal liability?
Who licenses insurance brokers in Alberta?
Is commercial auto insurance mandatory in Alberta?
How do I make a business insurance claim in Alberta?
Ready to compare?
Tell us about your business and we'll refer you to licensed brokers.